2027 Business Budget Planning: Review Your Risks
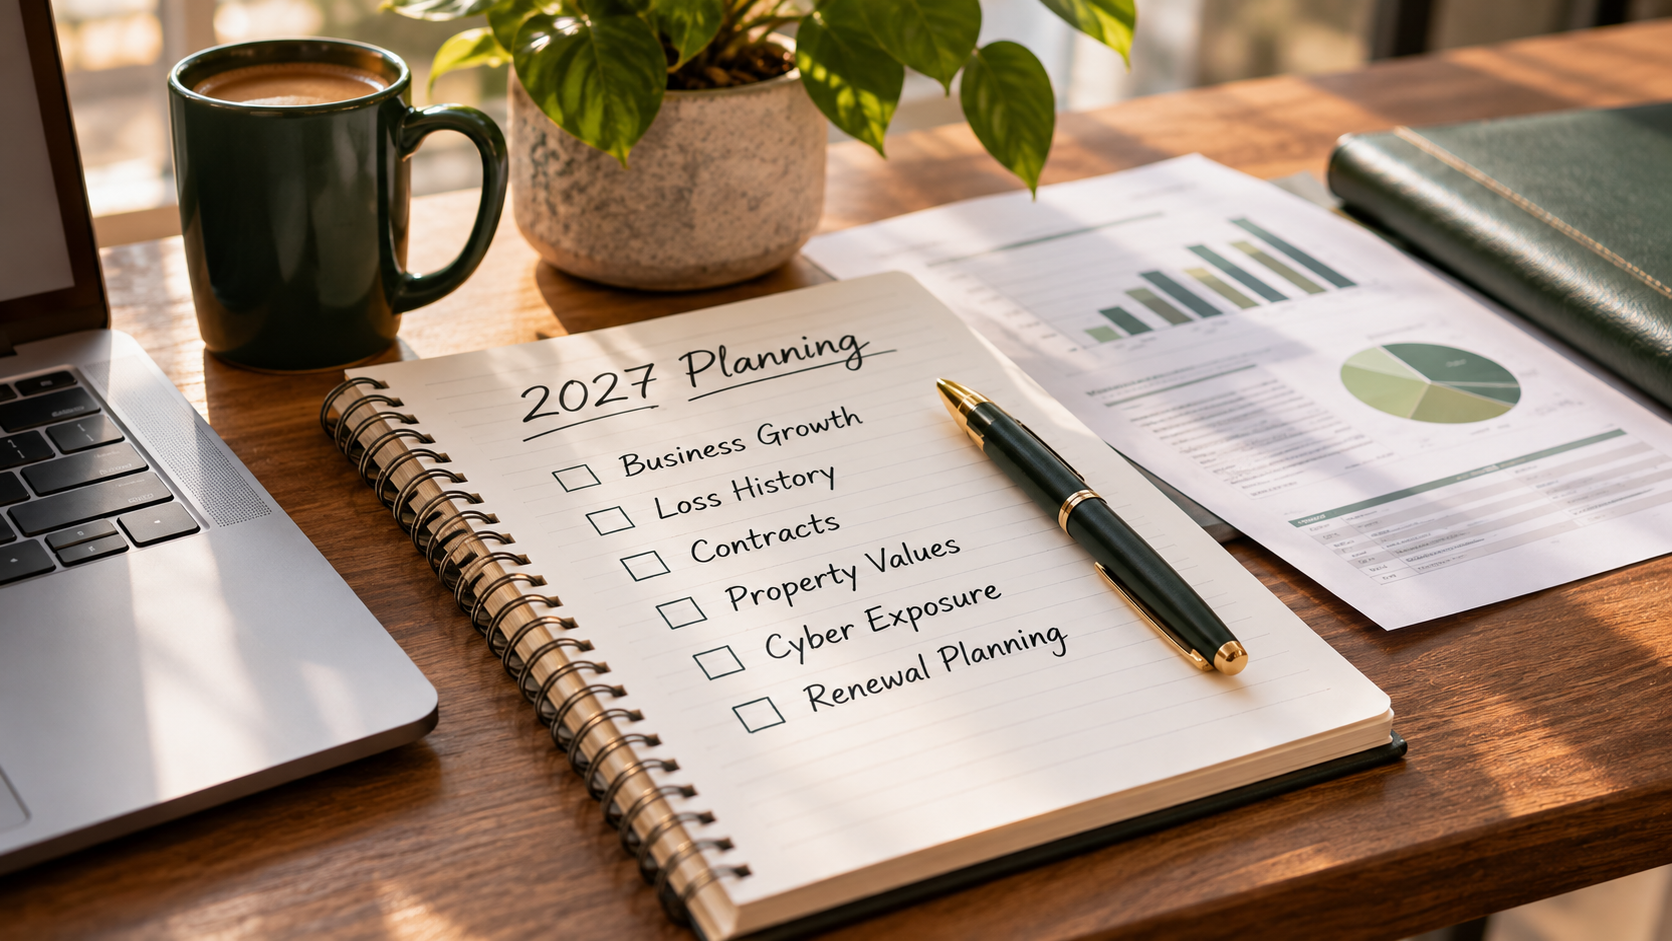
Before You Set Next Year's Budget, Have You Reviewed Your Biggest Business Risks?
As the year comes to a close, business owners are looking ahead. Budgets are being prepared, revenue goals are being established, and important decisions are being made about staffing, equipment, expansion, and future investments.
For many businesses, insurance is included in this planning process as a line-item expense. Owners review what they paid this year, estimate what premiums might look like next year, and move on to other priorities.
But there's an important question that deserves attention before finalizing your 2027 budget:
Has your business changed in ways that could affect your financial risk?
Your company may have grown, purchased new equipment, expanded services, hired additional employees, or accepted larger contracts. You may also be facing cybersecurity concerns, higher property replacement costs, or operational exposures that weren't present when your insurance policies were last reviewed.
These changes can influence more than your premiums. They can affect how much financial risk your business carries.
That's why year-end planning should involve more than comparing insurance prices. It's an opportunity to evaluate whether your risk-management strategy is keeping pace with your business.
Business Growth Can Change Your Insurance Needs
Growth is one of the most exciting parts of owning a business, but it can also introduce new responsibilities and exposures.
A contractor who started the year with three employees may now have eight. A retailer may have expanded its inventory or opened another location. A professional services firm may be serving larger clients or offering additional services.
Each of these changes can affect insurance considerations.
Increased payroll may influence workers' compensation premiums. Additional vehicles may change commercial auto exposure. New equipment or expanded facilities may require adjustments to property coverage.
Larger projects and contracts can also increase potential liability.
The insurance protection that made sense for your business at the beginning of 2026 may not fully reflect your operations heading into 2027.
Before finalizing your budget, consider what has changed and what growth is anticipated during the coming year.
A proactive insurance review can help identify areas where coverage, limits, or risk-management procedures may need attention.
What Can Your Claims History Tell You?
Your business's loss history provides valuable information about risks that have already affected your operations.
Even when claims are relatively small, reviewing them collectively can reveal patterns.
For example, repeated vehicle accidents may indicate a need for additional driver training or fleet safety procedures. Frequent property losses could point to maintenance concerns. Employee injuries may reveal opportunities to improve workplace safety practices.
A claims review shouldn't focus only on how much an insurer paid.
It should also consider deductibles, uninsured expenses, operational interruptions, and the time employees spent managing incidents.
Near misses and incidents that never became formal claims can also provide useful insight.
As you prepare your 2027 budget, ask whether there are preventive investments that could reduce the likelihood or severity of future losses.
Improved maintenance, employee training, updated safety procedures, or additional security measures may be worthwhile considerations.
Understanding what went wrong this year can help your business make better decisions about what to protect next year.
Are Your Contracts Creating Financial Obligations You Haven't Considered?
Contracts are an essential part of doing business, but they can also introduce responsibilities that aren't always obvious during the budgeting process.
A new customer agreement might require higher liability limits. A commercial lease may establish specific property insurance obligations. A subcontractor agreement could include indemnification provisions or additional insured requirements.
Some contracts also require specialized coverage, such as professional liability, cyber insurance, or commercial umbrella protection.
These requirements can affect both insurance costs and the financial responsibilities your business accepts.
It's important to remember that agreeing to an obligation in a contract doesn't automatically mean your insurance policy will cover it.
Certain contractual liabilities may be limited or excluded under existing policies.
Before entering into significant agreements for 2027, consider having qualified legal counsel review contractual terms and discussing insurance requirements with your Risk Advisor.
This can help identify potential mismatches between contractual obligations and available coverage before they create an unexpected problem.
Do Your Property Values Reflect Today's Replacement Costs?
Property insurance limits deserve particular attention during year-end planning.
The amount you originally paid for a building or piece of equipment may not represent what it would cost to replace today.
Construction materials, labor, equipment availability, and other market conditions can influence rebuilding and replacement expenses.
For example, a commercial building purchased several years ago may now require significantly more money to reconstruct after a major loss.
Businesses may also have made renovations, purchased machinery, installed technology, or increased inventory without updating their property values.
If insurance limits don't reflect current replacement costs, a covered loss could leave the business responsible for expenses beyond what its policy pays.
Some commercial property policies also include coinsurance provisions that may affect claim payments when required insurance amounts aren't maintained.
As part of your 2027 planning, review building values, business personal property limits, equipment schedules, and anticipated purchases.
The goal is to ensure your coverage reflects the assets your business needs to operate—not simply what those assets cost in the past.
Cyber Risk Should Be Part of Your Financial Planning
Cybersecurity is no longer a concern limited to large corporations or technology companies.
Businesses of all sizes rely on email, payment systems, customer databases, cloud applications, and other digital tools to operate.
A cyber incident could compromise sensitive information, interrupt essential systems, or result in fraudulent financial transactions.
The consequences may include investigation expenses, legal costs, recovery efforts, lost productivity, and damaged customer relationships.
As businesses adopt new technology, including artificial intelligence applications and cloud-based services, their exposure may continue to change.
Before finalizing next year's budget, evaluate whether your business has invested appropriately in cybersecurity measures.
Employee training, multifactor authentication, secure backups, software updates, and incident response planning are all important considerations.
Businesses should also review their cyber insurance protection.
Coverage for data breaches, business interruption, social engineering, and fraudulent transfers can vary significantly by policy.
A comprehensive risk assessment can help identify potential gaps between your technology-related exposures and existing insurance protection.
Don't Wait Until Renewal to Review Your Insurance
One of the most common mistakes businesses make is waiting until their insurance renewal date to evaluate coverage.
By that point, there may be limited time to review operations, update property values, gather underwriting information, or explore alternative coverage structures.
Starting the conversation early gives business owners and their Risk Advisors more time to evaluate potential changes.
This is especially important when a business has experienced significant growth, added locations, changed services, or faced claims during the policy period.
Renewal planning should consider more than whether premiums increased or decreased.
It should also examine deductibles, policy limits, exclusions, coverage enhancements, and the financial consequences of retaining certain risks.
The lowest premium doesn't necessarily represent the strongest protection for your business.
An effective insurance strategy should balance cost, coverage, and the specific exposures associated with your operations.
Six Questions to Ask Before Finalizing Your 2027 Budget
As you prepare for the coming year, consider these questions:
1. How has our business changed during 2026?
Review staffing, revenue, services, locations, vehicles, equipment, and operational responsibilities.
2. What did our claims and incident history reveal?
Identify recurring problems, near misses, and opportunities for prevention.
3. Have we accepted new contractual obligations?
Evaluate insurance requirements, indemnification provisions, and potential financial exposure.
4. Are our property values and coverage limits current?
Consider replacement costs, renovations, equipment purchases, and inventory changes.
5. Have our cybersecurity risks increased?
Review employee practices, technology systems, vendor relationships, and cyber insurance protection.
6. Are we planning for insurance renewal early enough?
Allow time to evaluate coverage options, address potential gaps, and make informed decisions.
These questions can help turn insurance from a routine budget expense into a more meaningful part of your business planning process.
A Stronger Budget Starts With a Clearer Understanding of Risk
Budgeting is about preparing your business for the year ahead.
That preparation should include understanding what could interrupt operations, create unexpected expenses, or threaten the assets you've worked hard to build.
A comprehensive risk review can help business owners make informed decisions about insurance protection, preventive investments, and financial planning.
It can also reveal opportunities to strengthen business continuity, improve safety procedures, and reduce unnecessary exposure.
While no business can eliminate every risk, proactive planning can help reduce surprises and improve financial resilience.
Before deciding what insurance should cost in 2027, make sure you understand what your business needs to protect.
Make Risk Management Part of Your 2027 Business Plan
As you establish financial goals and prepare your budget for the coming year, don't overlook the importance of reviewing your insurance and risk-management strategy.
Your business may look very different today than it did twelve months ago.
At Fortis Risk Group, we believe protecting your business begins with understanding where you are, where you're going, and what risks could stand in the way.
Contact a Fortis Risk Advisor for a comprehensive policy and risk review before finalizing your 2027 budget.
Our team can help you evaluate changes in your operations, review existing insurance protection, identify potential coverage gaps, and develop a proactive risk-management strategy aligned with your business goals.
Because planning for growth should also mean planning for protection.
Listen. Lead. Protect.
Latest insights and trends
Commercial Fleet Safety Tips for the Holiday Season
Professional Liability vs. General Liability: What's the Difference

Fall Storm Preparedness for Small Businesses
Are Your Employees Using AI Safely? Business Risks
Let’s Build Your Protection Strategy