5 Photos Every Business Needs Before a Claim

The Photos You Need Before an Insurance Claim Happens
Imagine walking into your business after a severe storm, fire, or other unexpected event and discovering significant damage.
Your first priorities are safety, protecting your employees, and getting your operations back on track. But once the immediate situation is under control, another important question comes up:
Can you prove what your business owned and what condition it was in before the damage occurred?
For many business owners, the answer isn't as straightforward as they might expect.
You may know exactly what equipment you purchased, how much inventory you typically carry, or what improvements you've made to your building. But remembering those details and documenting them for an insurance claim are two different things.
That's why one of the simplest forms of proactive risk mitigation is also one of the most overlooked: taking photos before something goes wrong.
Why Photos Matter During an Insurance Claim
When a covered loss occurs, your insurance company will typically need information to evaluate the damage and determine how the policy applies.
Photos taken before an incident can help establish the condition, location, and existence of business property.
While photographs don't guarantee coverage or determine the amount of a claim payment, they can provide valuable supporting documentation alongside receipts, purchase records, inventory reports, appraisals, and maintenance records.
The best time to collect that information is when everything is operating normally—not after a disaster.
1. Photograph Your Building Inside and Out
Start with the physical structure of your business.
Take clear photographs of the exterior, including the roof where safely visible, entrances, windows, signage, exterior walls, parking areas, and surrounding property.
Inside, document offices, storage areas, production spaces, electrical and mechanical equipment, flooring, fixtures, and other significant building features.
These images can help establish the property's condition before damage occurs.
Risk Advisor Tip: Update your building photographs after major renovations, repairs, or improvements.
2. Document Equipment, Machinery, and Tools
For many businesses, equipment represents a substantial financial investment.
A contractor may depend on specialized tools. A restaurant may rely on commercial kitchen equipment. A manufacturer may have expensive machinery essential to daily operations.
Photograph each major piece of equipment, including its overall condition and any identifying information.
Whenever possible, capture:
- Manufacturer and model
- Serial number
- Equipment location
- General condition
- Installed accessories or attachments
Keep purchase receipts, service records, and equipment schedules with your documentation.
This information can be especially useful when determining what needs to be repaired or replaced following a covered loss.
3. Don't Overlook Inventory
Inventory changes constantly.
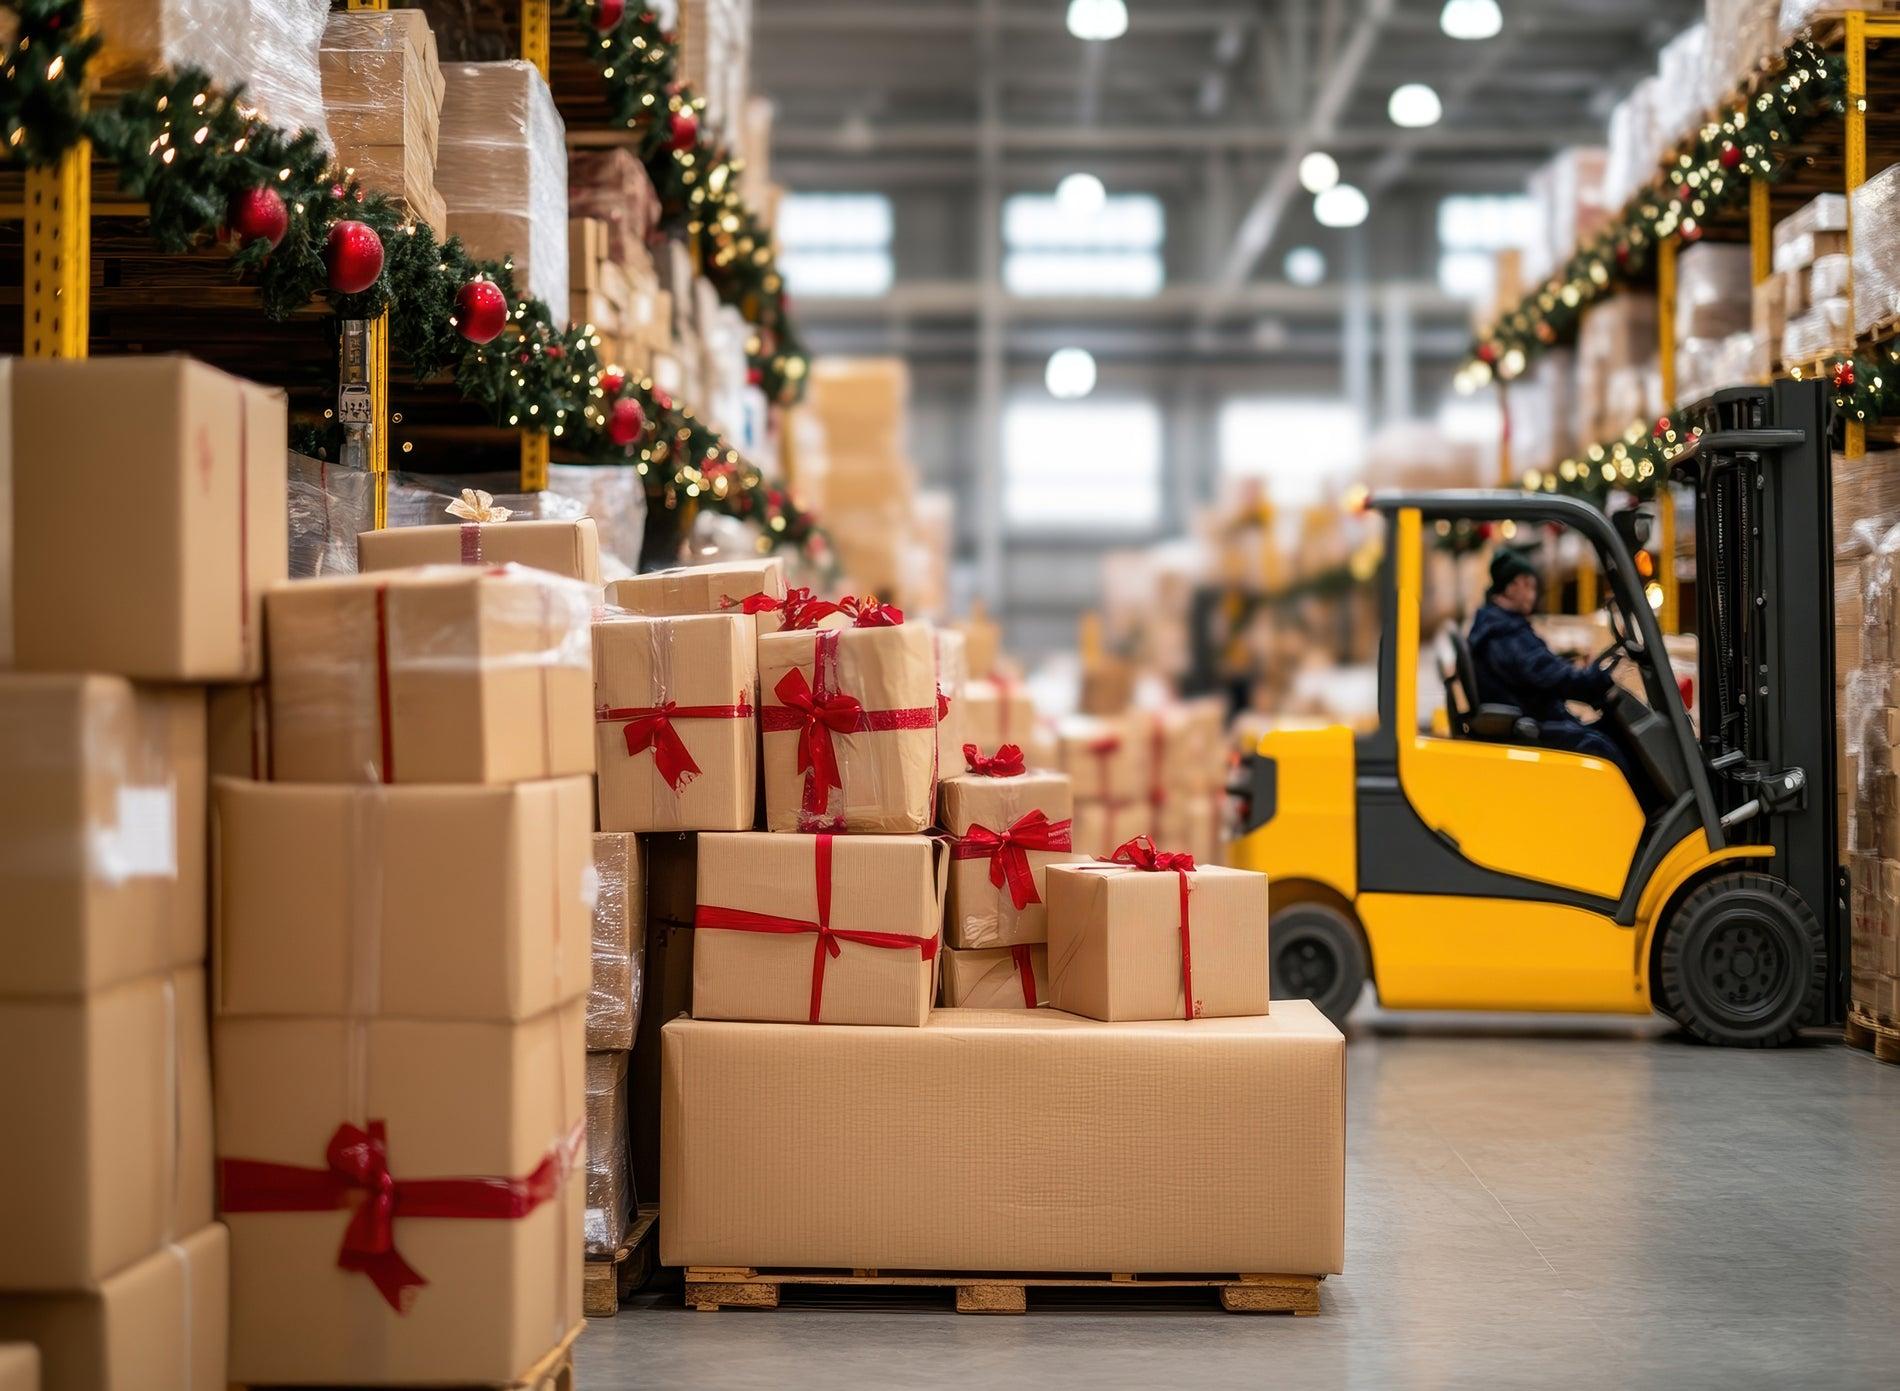
Whether your business sells retail merchandise, stores construction materials, distributes products, or maintains supplies for daily operations, those items may represent significant value.
Take photographs of storage shelves, stockrooms, warehouses, and other inventory areas.
For high-value items, consider individual photographs and more detailed records.
Photos should supplement—not replace—an accurate inventory management system.
Important: If your inventory increases during certain seasons, update your documentation to reflect those changes.
4. Capture Serial Numbers and Identification Plates
After a significant loss, identifying specific equipment can become difficult.
Serial numbers, model numbers, and manufacturer labels help distinguish one piece of equipment from another.
Photograph identification plates on computers, machinery, generators, appliances, specialized tools, and other valuable business assets.
For additional protection, maintain a digital asset list connecting those photographs to purchase dates, values, and equipment descriptions.
A few extra minutes of documentation today could save considerable time later.
5. Record Renovations and Property Improvements
Has your business recently installed new flooring, upgraded electrical systems, replaced HVAC equipment, expanded a workspace, or completed a major renovation?
Those improvements may increase the value of your property or change your insurance needs.
Photograph completed improvements and maintain copies of contractor invoices, permits, and relevant project documentation.
Don't assume your current insurance limits automatically reflect every improvement you've made.
Significant changes should also trigger a conversation with your Risk Advisor about replacement costs and coverage limits.
Where Should You Store Your Photos?
Taking photographs is only helpful if you can access them after a loss.
If every photo is stored on a computer inside the damaged building, you could lose the documentation when you need it most.
Consider maintaining an organized, securely backed-up digital record that includes photographs, inventory lists, receipts, equipment information, and improvement records.
Use appropriate access controls to protect sensitive business information.
Review and update your records at least annually, and whenever you make significant purchases or operational changes.
Documentation Is Part of a Stronger Risk Strategy
Insurance is designed to help businesses manage certain financial losses, but having a policy is only one part of being prepared.
A comprehensive risk-management strategy also considers property maintenance, disaster planning, employee safety, business continuity, accurate asset valuations, and claims documentation.
Photographs help support that preparation.
They can also prompt an important question:
Does your current insurance reflect everything your business owns today?
If you've purchased equipment, expanded inventory, renovated your property, or added valuable assets, your exposure may have changed since your last insurance review.
Prepare Before You Need to File a Claim
You can't always prevent a storm, fire, theft, or unexpected accident.
But you can take steps today to make the aftermath easier to navigate.
Set aside time this month to walk through your business, photograph your property, document your assets, and organize your records.
A little preparation now can make a meaningful difference when the unexpected happens.
Is Your Business Prepared for the Unexpected?
Knowing what you own is important. Knowing whether it's properly protected is just as important.
Contact a Fortis Risk Advisor for a comprehensive policy and risk review. Our team can help you evaluate your property values, equipment, inventory, recent improvements, and potential coverage gaps while developing a proactive risk-management strategy designed to protect the business you've worked hard to build.
Listen. Lead. Protect.
Latest insights and trends

Let’s Build Your Protection Strategy