Holiday Inventory: Are Your Insurance Limits Enough?
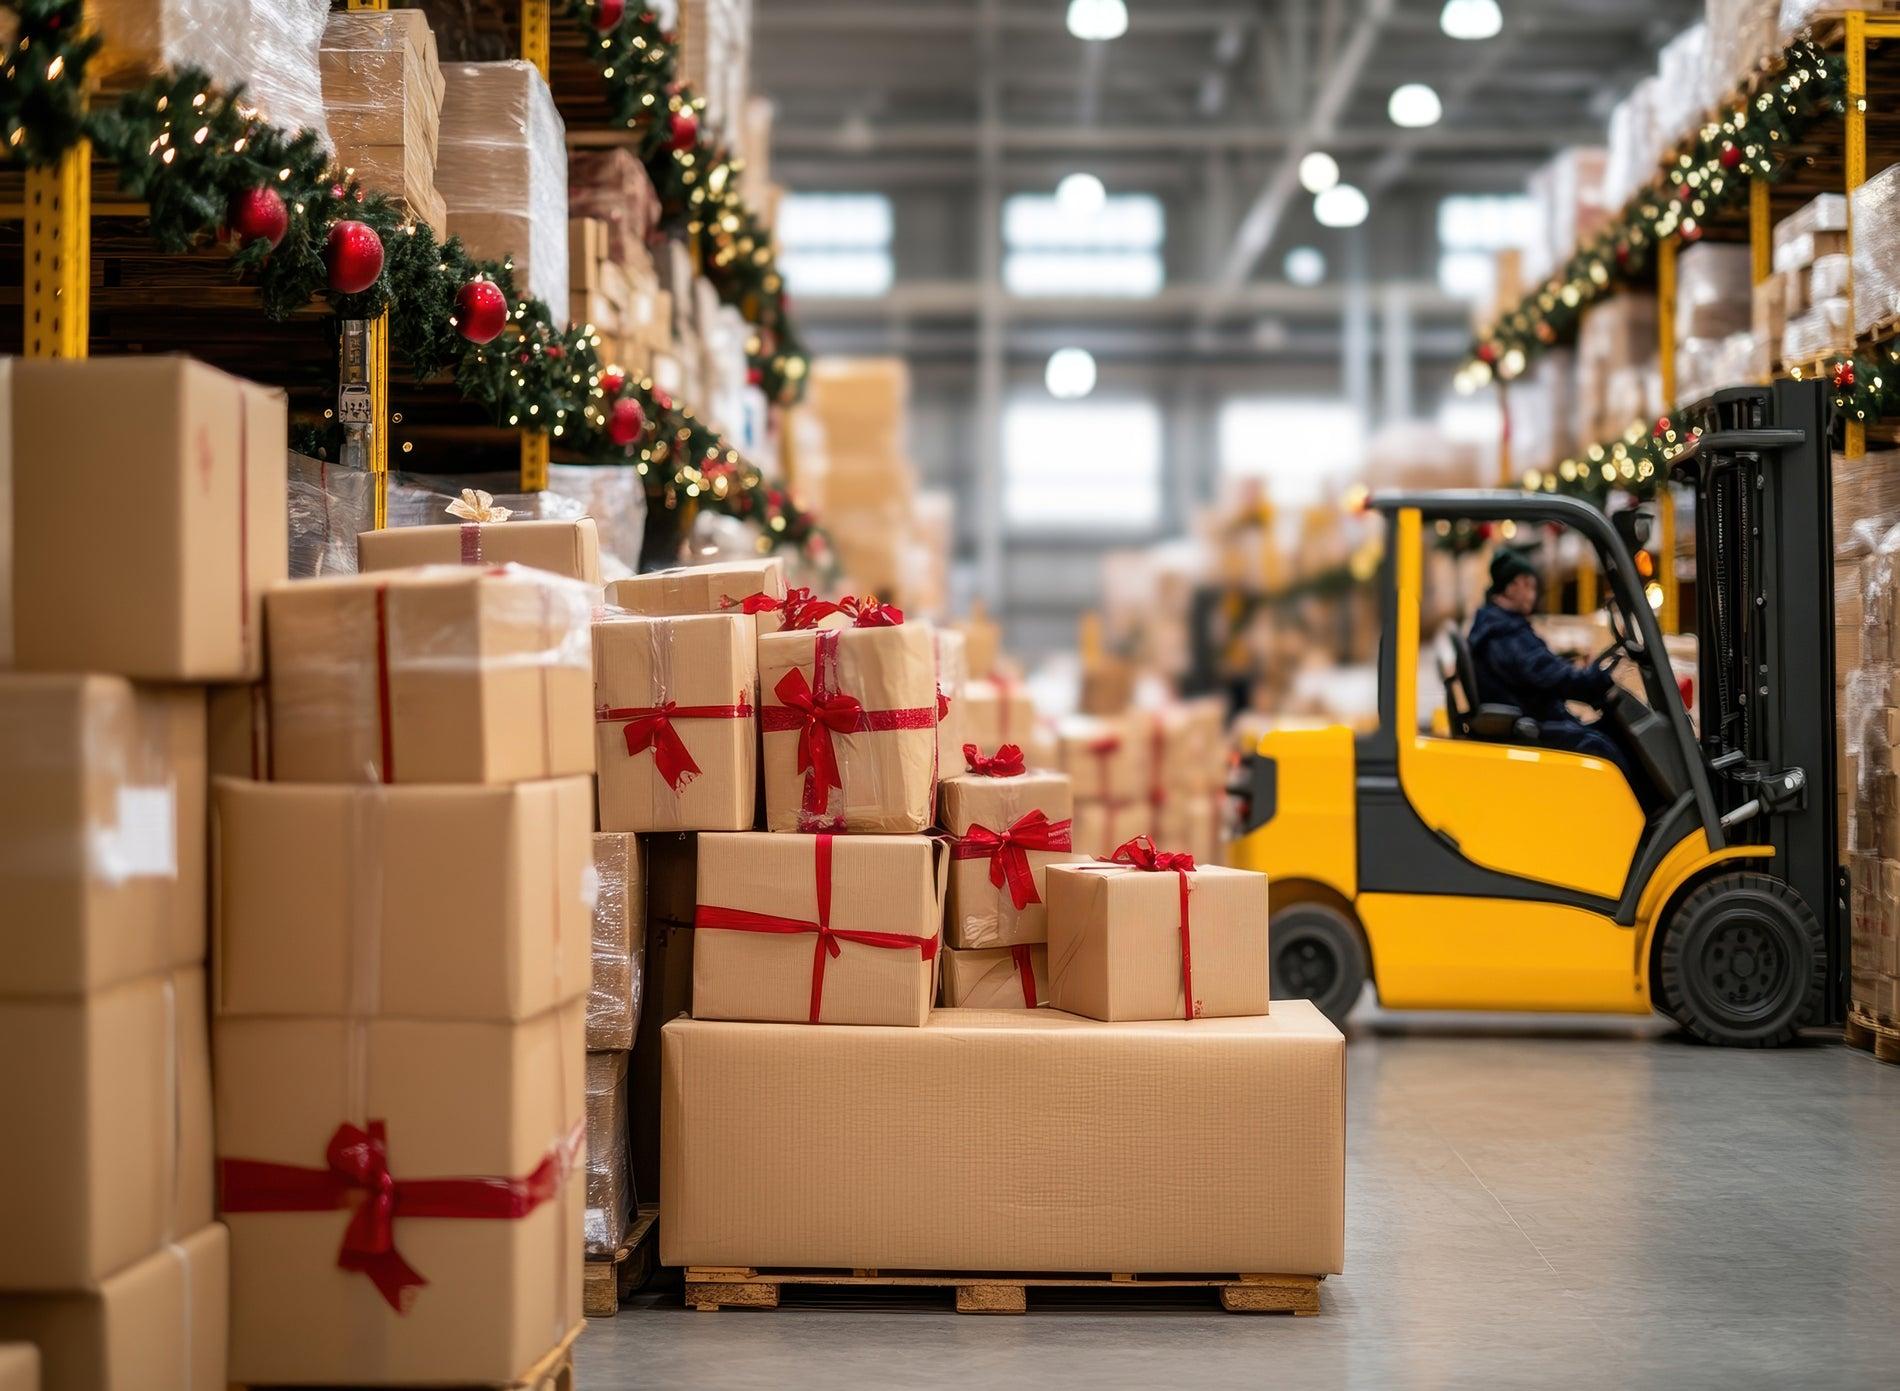
Holiday Inventory Is Increasing. Are Your Insurance Limits Keeping Up?
For many businesses, the final months of the year bring increased activity, higher sales expectations, and a growing amount of inventory.
Retailers are stocking shelves for holiday shoppers. Restaurants are ordering additional supplies for seasonal events. Distributors are preparing for increased demand, and warehouses are filling with merchandise that may not remain on-site for long.
While this seasonal growth creates opportunities for revenue, it also introduces a question business owners may overlook:
If your business experienced a major loss today, would your insurance limits reflect the actual value of everything you're storing?
The answer matters more than you might think.
When inventory levels increase, your financial exposure can increase right alongside them. Without a proactive insurance review, your business could enter its busiest season carrying more risk than its current coverage was designed to address.
Why Holiday Inventory Creates Additional Risk
Most businesses have a general understanding of how much inventory they carry throughout the year.
However, those numbers can change significantly during peak seasons.
A retailer that typically maintains $75,000 in merchandise might temporarily increase its inventory to $150,000 in anticipation of holiday demand.
If that business experiences a fire, theft, or another covered loss during its busiest period, the amount of property at risk could be substantially higher than usual.
This is where commercial property insurance becomes especially important.
Business personal property coverage may help protect inventory, equipment, furniture, and other eligible business assets against certain covered causes of loss.
But coverage is subject to policy limits, deductibles, conditions, and exclusions.
Having commercial property insurance doesn't automatically mean every dollar of seasonal inventory is adequately protected.
That's why understanding your peak inventory value—not just your average inventory—is an important part of risk planning.
Do Your Insurance Limits Account for Seasonal Stock Increases?
Some commercial property policies include provisions that may accommodate seasonal increases in inventory. Others may require adjustments, endorsements, or specific reporting procedures.
The details depend on the policy.
Business owners should never assume their coverage automatically increases simply because they've purchased additional merchandise.
For example, a policy may have a business personal property limit based on normal operating conditions.
If inventory values rise substantially during November and December, that limit may no longer reflect the business's total exposure.
A comprehensive insurance review can help determine whether your policy includes seasonal increase provisions, whether additional coverage is appropriate, and how inventory values should be reported.
Risk Advisor Tip: Review your anticipated peak inventory levels before the merchandise arrives, rather than waiting until your storage areas are full.
Temporary Storage Can Create Unexpected Coverage Gaps
When businesses run out of room, they often find creative solutions.
Additional merchandise might be stored in a rented warehouse, a temporary storage unit, an off-site facility, or another business location.
While these arrangements may solve a space problem, they can also create insurance questions.
Not every commercial property policy provides the same level of protection for property stored away from the insured premises.
Coverage may depend on where the property is located, who owns or controls the storage facility, and whether the location has been disclosed to the insurance company.
There may also be separate limits or conditions for property in transit.
Before moving valuable inventory, consider asking:
- Is merchandise covered at the temporary location?
- Are there separate limits for off-site storage?
- Does the policy cover inventory while it's being transported?
- Are there security or reporting requirements?
- Does the storage agreement create additional insurance obligations?
These details are worth reviewing before a loss occurs.
More Inventory Can Mean Greater Theft Exposure
The holiday season often brings increased foot traffic, more deliveries, extended operating hours, and a higher volume of merchandise moving through business locations.
Each of these changes can affect security.
For retailers, theft may involve shoplifting, employee dishonesty, or merchandise disappearing during busy shifts.
For warehouses and distributors, risks may include unauthorized access, shipment theft, and inventory discrepancies.
Businesses should evaluate their security procedures before the holiday rush.
Practical precautions include reviewing surveillance systems, securing high-value merchandise, limiting access to storage areas, verifying deliveries, and maintaining accurate inventory records.
It's also important to understand that not all types of theft are treated the same under commercial insurance policies.
Employee theft, burglary, unexplained inventory shortages, and other losses may be subject to different coverage provisions or exclusions.
Some exposures may require commercial crime insurance or additional endorsements.
A Risk Advisor can help identify where your existing protection may or may not respond.
What Happens If Inventory Loss Interrupts Your Business?
The financial consequences of losing inventory can extend beyond the value of the merchandise itself.
Imagine a retailer experiencing a covered fire just weeks before its busiest shopping period.
The immediate loss includes damaged products, but the business may also face canceled orders, delayed deliveries, lost sales opportunities, and additional expenses associated with resuming operations.
Depending on the circumstances, business income and extra expense coverage may help address certain financial consequences of a covered interruption.
However, these coverages have specific requirements, limits, waiting periods, and exclusions.
The amount of lost income a business experiences doesn't necessarily equal the amount an insurance policy will pay.
That's why seasonal risk assessments should consider both the value of inventory and the potential operational impact of losing access to it.
Keep Your Inventory Records Current
Accurate documentation can be valuable if your business needs to file an insurance claim.
During peak season, make sure your inventory records reflect the merchandise actually on hand.
Consider maintaining updated inventory reports, purchase invoices, supplier records, photographs, and documentation of high-value items.
If you use inventory management software, verify that the information is current and securely backed up.
Photographs of storage areas, shelving, and merchandise can also help establish the condition and quantity of inventory before a loss.
The more organized your documentation is before an incident, the easier it may be to provide supporting information during the claims process.
Five Questions to Ask Before Your Holiday Inventory Arrives
Before entering your busiest season, take a few minutes to evaluate your exposure.
1. What is the highest inventory value we expect to carry?
Consider peak stock levels rather than relying solely on annual averages.
2. Does our property insurance reflect that value?
Review business personal property limits and any seasonal inventory provisions.
3. Are we using additional storage locations?
Confirm how coverage applies to temporary warehouses, rented facilities, and off-site merchandise.
4. Have our theft and security risks changed?
Evaluate access controls, delivery procedures, surveillance, and employee responsibilities.
5. Could a major inventory loss interrupt our operations?
Consider how damaged or unavailable merchandise could affect revenue, customers, and your ability to fulfill orders.
These questions can help reveal exposures that deserve attention before the holiday season reaches its peak.
Don't Let a Successful Season Create an Insurance Surprise
A busy holiday season should be an opportunity for business growth—not an unexpected increase in financial vulnerability.
As inventory levels rise, businesses should take time to evaluate whether their property limits, storage arrangements, security practices, and business continuity plans are keeping pace.
Insurance needs aren't static.
They change as businesses grow, purchase additional assets, expand operations, and prepare for seasonal demand.
The best time to identify a coverage gap is before a claim reveals it.
Is Your Business Ready for the Holiday Rush?
Whether you're stocking retail shelves, expanding warehouse inventory, or preparing for seasonal demand, your insurance strategy should reflect the risks your business faces today.
Contact a Fortis Risk Advisor for a comprehensive policy and risk review.
Our team can help you evaluate your commercial property limits, seasonal inventory exposure, temporary storage arrangements, and potential coverage gaps so you can approach the holiday season with greater confidence.
At Fortis Risk Group, we believe protecting your business starts with understanding your risks before they become losses.
Listen. Lead. Protect.
Latest insights and trends


Let’s Build Your Protection Strategy