Could an Employee Lawsuit Put Your Business at Risk?
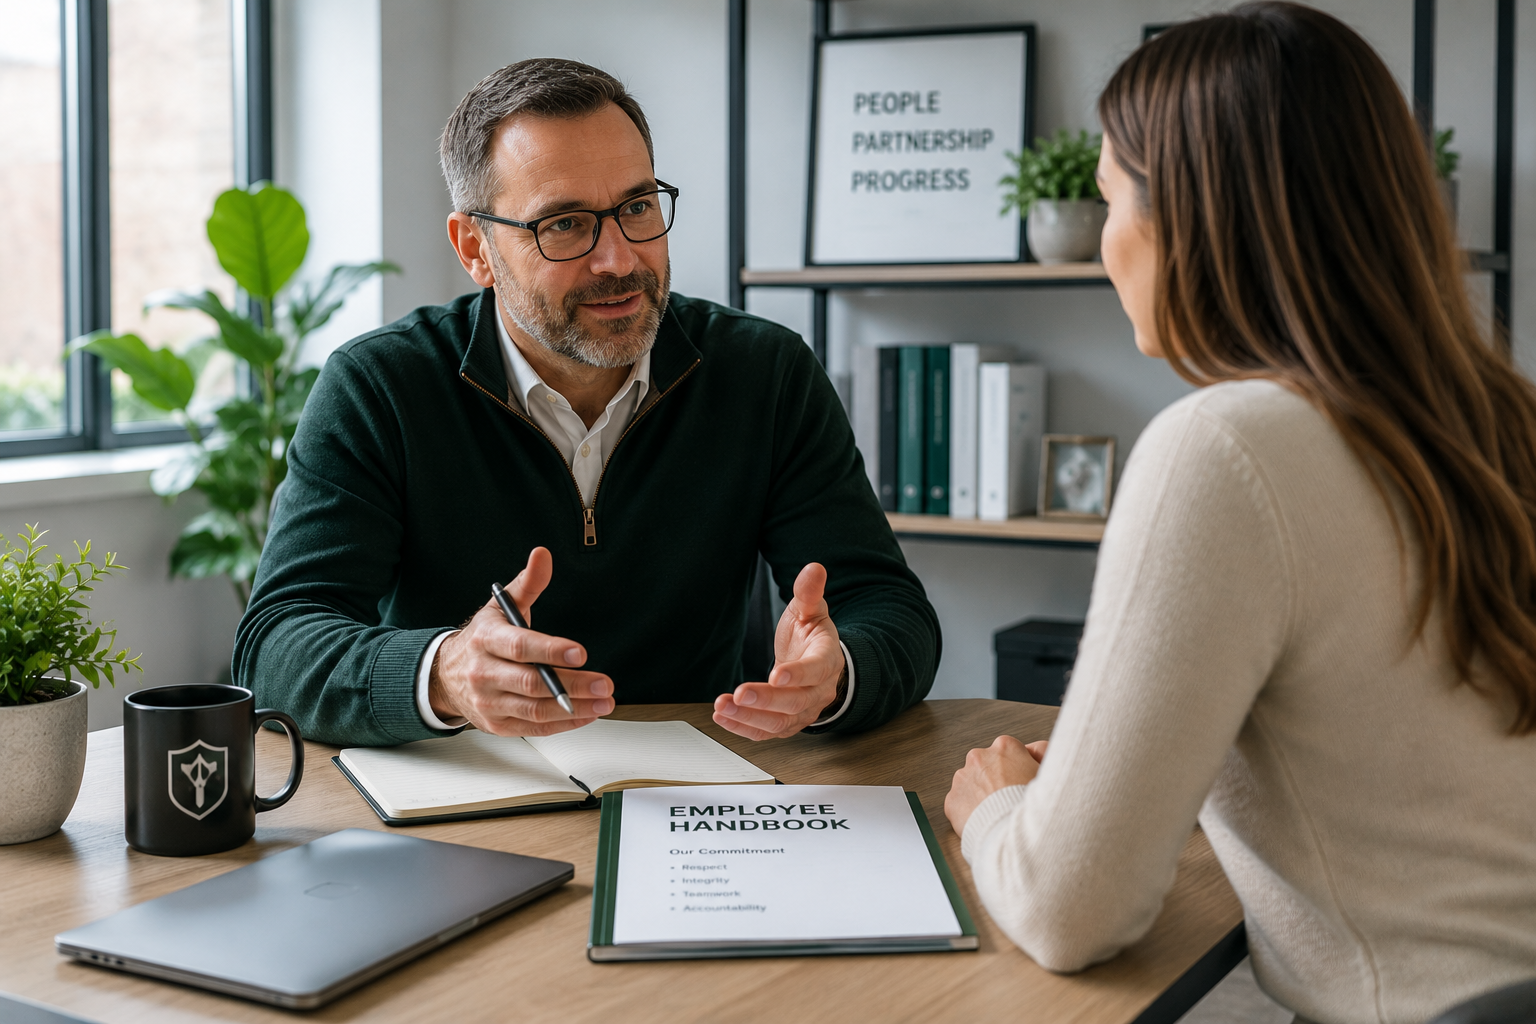
Could an Employee Lawsuit Put Your Business at Risk? Understanding EPLI
Your business carries general liability insurance. You have workers' compensation. Your property is insured.
So if an employee files a lawsuit against your company, you're covered—right?
Not necessarily.
One of the most important parts of building a strong business insurance program is understanding that different risks may require different types of protection. Claims involving employees and employment practices can create exposures that aren't the same as a customer slipping and falling at your business or a storm damaging your property.
That's where Employment Practices Liability Insurance, commonly called EPLI, enters the conversation.
What Is Employment Practices Liability Insurance?
EPLI is designed to provide coverage for certain claims involving employment-related practices, subject to the terms, conditions, limits, and exclusions of the specific policy.
Depending on the policy and circumstances, allegations could involve issues such as:
- Wrongful termination
- Discrimination
- Harassment
- Retaliation
- Failure to promote
- Certain hiring-related claims
- Other alleged inappropriate workplace conduct
The important takeaway for business owners is that general liability insurance shouldn't automatically be assumed to cover an employment-related lawsuit.
Your overall insurance program should be reviewed to determine how these risks are addressed.
"But We're a Small Business."
Small businesses sometimes assume EPLI is primarily a concern for large corporations with hundreds or thousands of employees.
But employment disputes aren't limited to large companies.
In fact, a small business can be especially vulnerable to the financial impact of a dispute because it may have fewer resources available to absorb legal expenses or unexpected losses.
Even when a business believes it acted appropriately, responding to an allegation can require time, documentation, legal assistance, and management attention.
The risk isn't simply whether your company will ultimately be found responsible. It's also the cost and disruption associated with responding to the situation.
Your Risk Begins Before Someone Is Hired
Employment-related risk doesn't necessarily begin on an employee's first day.
Your hiring advertisements, interview process, background screening practices, job descriptions, onboarding procedures, employee handbook, disciplinary practices, and termination procedures can all play a role in your overall employment risk.
That's why EPLI should be considered alongside proactive risk mitigation.
Insurance can provide important financial protection, but strong internal practices can help businesses reduce the likelihood of problems developing in the first place.
Five Questions Every Employer Should Ask
Take a quick look at your current employment practices.
1. When was your employee handbook last reviewed?
Policies should reflect how your business actually operates today.
2. Do managers document employee performance issues?
Consistent documentation can become extremely important when employment decisions are questioned.
3. Do employees know how to report workplace concerns?
Your organization should have a clear process for raising concerns before problems escalate.
4. Are supervisors trained?
Someone can be an excellent employee or manager while still needing guidance on interviewing, discipline, harassment prevention, and other employment practices.
5. Has your workforce changed?
Rapid hiring, remote employees, new locations, and changes in management can all affect your risk profile.
Growth Can Change Your Employment Exposure
A company with three employees has a different risk profile than one with 30.
As your workforce expands, there are more interactions, more management decisions, and potentially more opportunities for misunderstandings or disputes.
Your insurance and risk-management strategy should grow with your organization.
Don't wait until a claim occurs to discover that your current coverage was designed for a much smaller or different business.
Insurance Is Only One Piece of the Solution
At Fortis Risk Group, we believe the strongest approach combines appropriate insurance protection with proactive risk management.
That means looking beyond the policy itself.
A Risk Advisor can help you evaluate where employment-related exposures fit within your overall insurance program, while qualified legal and human resources professionals can help you develop appropriate workplace policies and procedures.
The goal isn't simply to prepare for a lawsuit.
It's to build a stronger organization that reduces the likelihood of one happening.
Is Employment Risk Part of Your Insurance Review?
If you have employees, your people are one of your greatest business assets—but managing a workforce also creates responsibilities and risks that deserve attention.
Contact one of the Risk Advisors at Fortis Risk Group for a comprehensive policy and risk review. We'll help you evaluate your current employment-related insurance exposures, identify potential coverage gaps, and determine whether your protection has kept pace with your workforce and business growth.
Latest insights and trends

Why Did My Workers' Comp Audit Result in a Bill?

Business Insurance Rates: Should You Shop Before Renewal?
What Goes Into a Business Insurance Quote?
Let’s Build Your Protection Strategy