Workers' Comp Audit? Avoid These Common Surprises
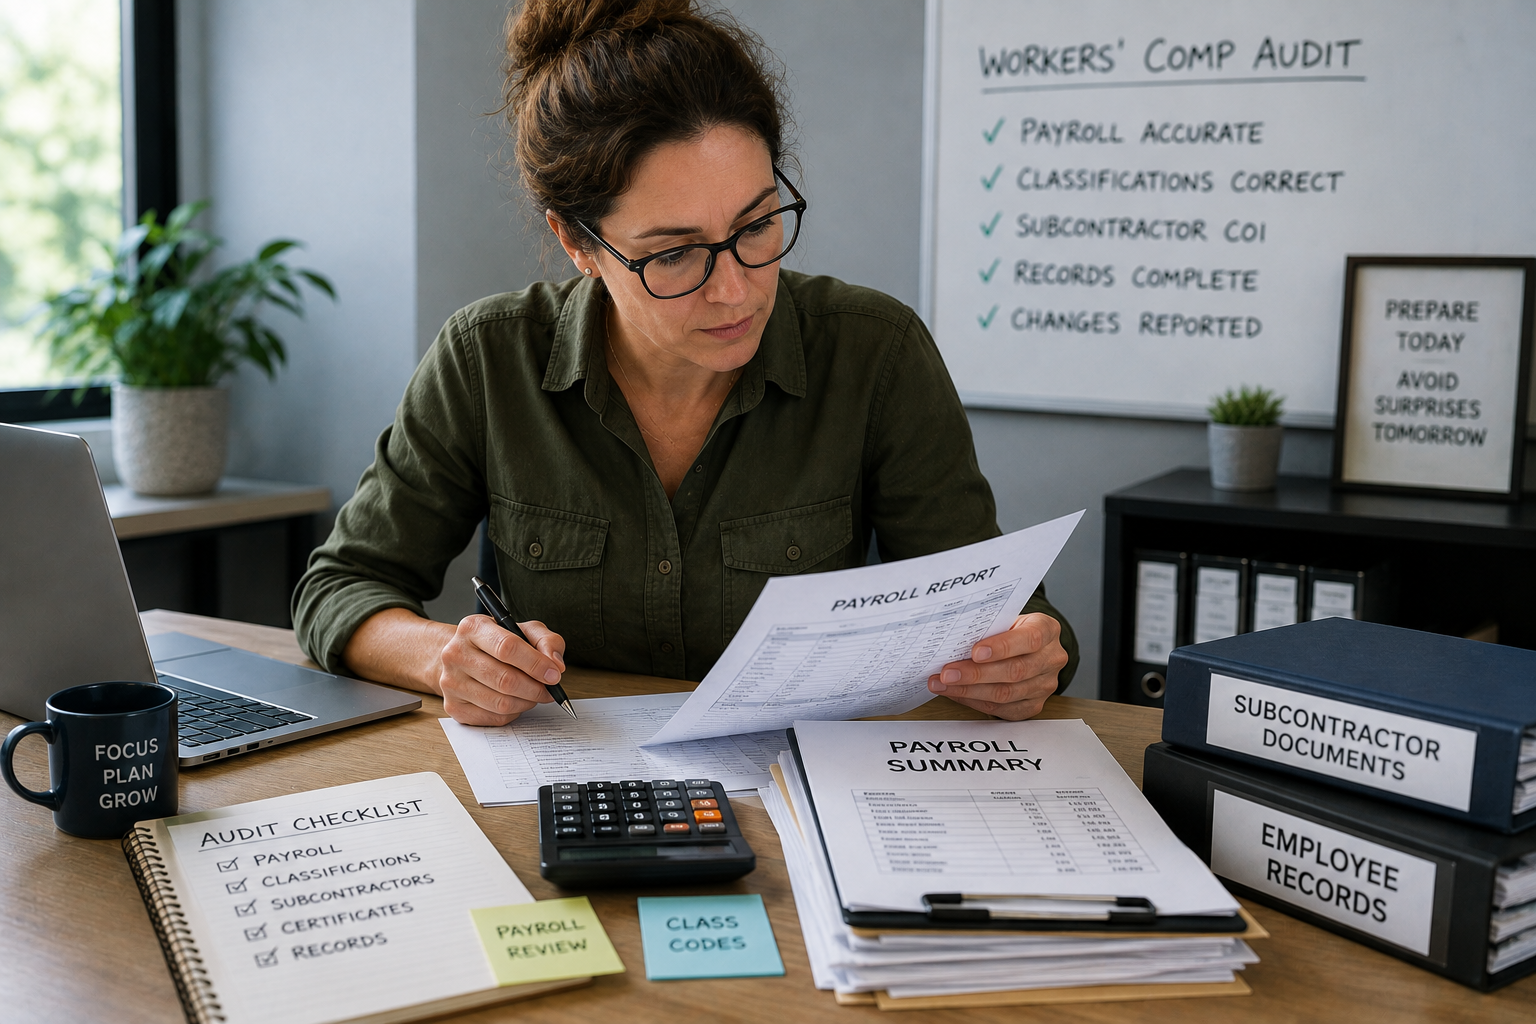
Workers' Comp Audit Surprises: Are Your Payroll and Employee Classifications Accurate?
You budgeted for your workers' compensation insurance at the beginning of the policy year. Then audit time arrives—and suddenly your business owes additional premium.
For a small-business owner, that can be frustrating.
But a workers' compensation audit isn't necessarily an unexpected fee added at the end of the year. In many cases, it is a reconciliation between the payroll and operations estimated when the policy began and what actually happened during the policy period.
If your business grew, hired employees, changed operations, or used subcontractors, your actual exposure may look very different from the original estimate.
That's why workers' compensation should be reviewed throughout the year—not only when the auditor calls.
Why Do Workers' Compensation Audits Happen?
Workers' compensation premiums are commonly influenced by factors such as payroll, employee job classifications, and the nature of the work being performed.
At the beginning of a policy term, some of those numbers may be based on estimates.
But businesses change.
Maybe you expected $500,000 in payroll and finished the year at $700,000. Perhaps you hired additional employees, added a new type of work, or expanded a department.
The audit helps determine what the actual exposure was during the policy period.
Depending on the results and policy terms, that can lead to an additional premium or potentially a return premium.
1. Has Your Payroll Increased?
Payroll growth is one of the first areas to review.
If you've added employees, increased wages, expanded hours, or experienced faster-than-expected growth, your estimated payroll may no longer reflect reality.
Instead of waiting until the end of the policy term, notify your Risk Advisor when significant payroll changes occur.
Updating estimates during the year can help reduce the possibility of a large adjustment later.
2. Are Employees Classified Correctly?
Workers' compensation classification codes generally reflect the type of work employees perform.
Not every employee presents the same workplace exposure.
An administrative employee working primarily at a desk, for example, may have a very different risk profile than an employee performing roofing, electrical, manufacturing, landscaping, or construction work.
Incorrect classifications can create insurance and audit issues.
Business owners should avoid guessing which classifications apply. Instead, work with insurance professionals to accurately describe what employees actually do.
3. Have Employees Changed Roles?
Job responsibilities evolve.
An employee originally hired for administrative work may begin spending significant time in the field. Your company may introduce a new service or create an entirely new position.
Those changes should be part of your insurance review.
Your policy should reflect how the business operates today—not simply the job descriptions that existed when the policy was first written.
4. Are You Keeping Records for Subcontractors?
Subcontractors can become an important issue during workers' compensation audits.
Businesses should maintain organized records for subcontractors and collect appropriate Certificates of Insurance when required.
Depending on the circumstances, applicable law, policy terms, and documentation, uninsured subcontractor labor can create additional exposure during an audit.
Don't wait until audit time to start searching through emails for certificates and invoices.
Create a process for collecting and maintaining documentation throughout the year.
5. Has Your Business Added New Operations?
Perhaps a contractor added a new trade. A retailer began making deliveries. A manufacturer introduced another production process.
Changes in operations can affect your risk profile and potentially your workers' compensation classifications.
This is exactly why proactive risk mitigation matters.
Your Risk Advisor can't help evaluate a change they don't know happened.
Make Audit Preparation an Ongoing Process
Workers' compensation audit preparation doesn't have to begin when the audit notice arrives.
Throughout the year, keep accurate records of:
- Payroll
- Employee job duties
- New hires and terminations
- Overtime when applicable
- Subcontractor payments
- Certificates of Insurance
- Changes in business operations
Good records can make the audit process much smoother and give your Risk Advisor better information when evaluating your coverage.
Don't Let Growth Become an Audit Surprise
A growing payroll is often good news—it means your company may be expanding.
The problem occurs when your insurance estimates don't grow with it.
Regular risk reviews can help align your workers' compensation program with your actual workforce and operations.
Is Your Workers' Comp Policy Keeping Up?
If your payroll, employees, subcontractors, or operations have changed this year, don't wait for your next audit to find out whether your insurance reflects those changes.
Contact one of the Risk Advisors at Fortis Risk Group for a comprehensive policy and risk review. We'll help evaluate your workers' compensation exposures, payroll estimates, classifications, and business changes so you can approach audit time with fewer surprises and a stronger risk-management strategy.
Latest insights and trends
Let’s Build Your Protection Strategy